NovAsia

Developer installments · Cambodia focus

Overseas property on a developer installment plan

Projects to compare

Projects for this topic

Prices are starting-market indications; confirm the final unit, availability and payment plan before a decision.

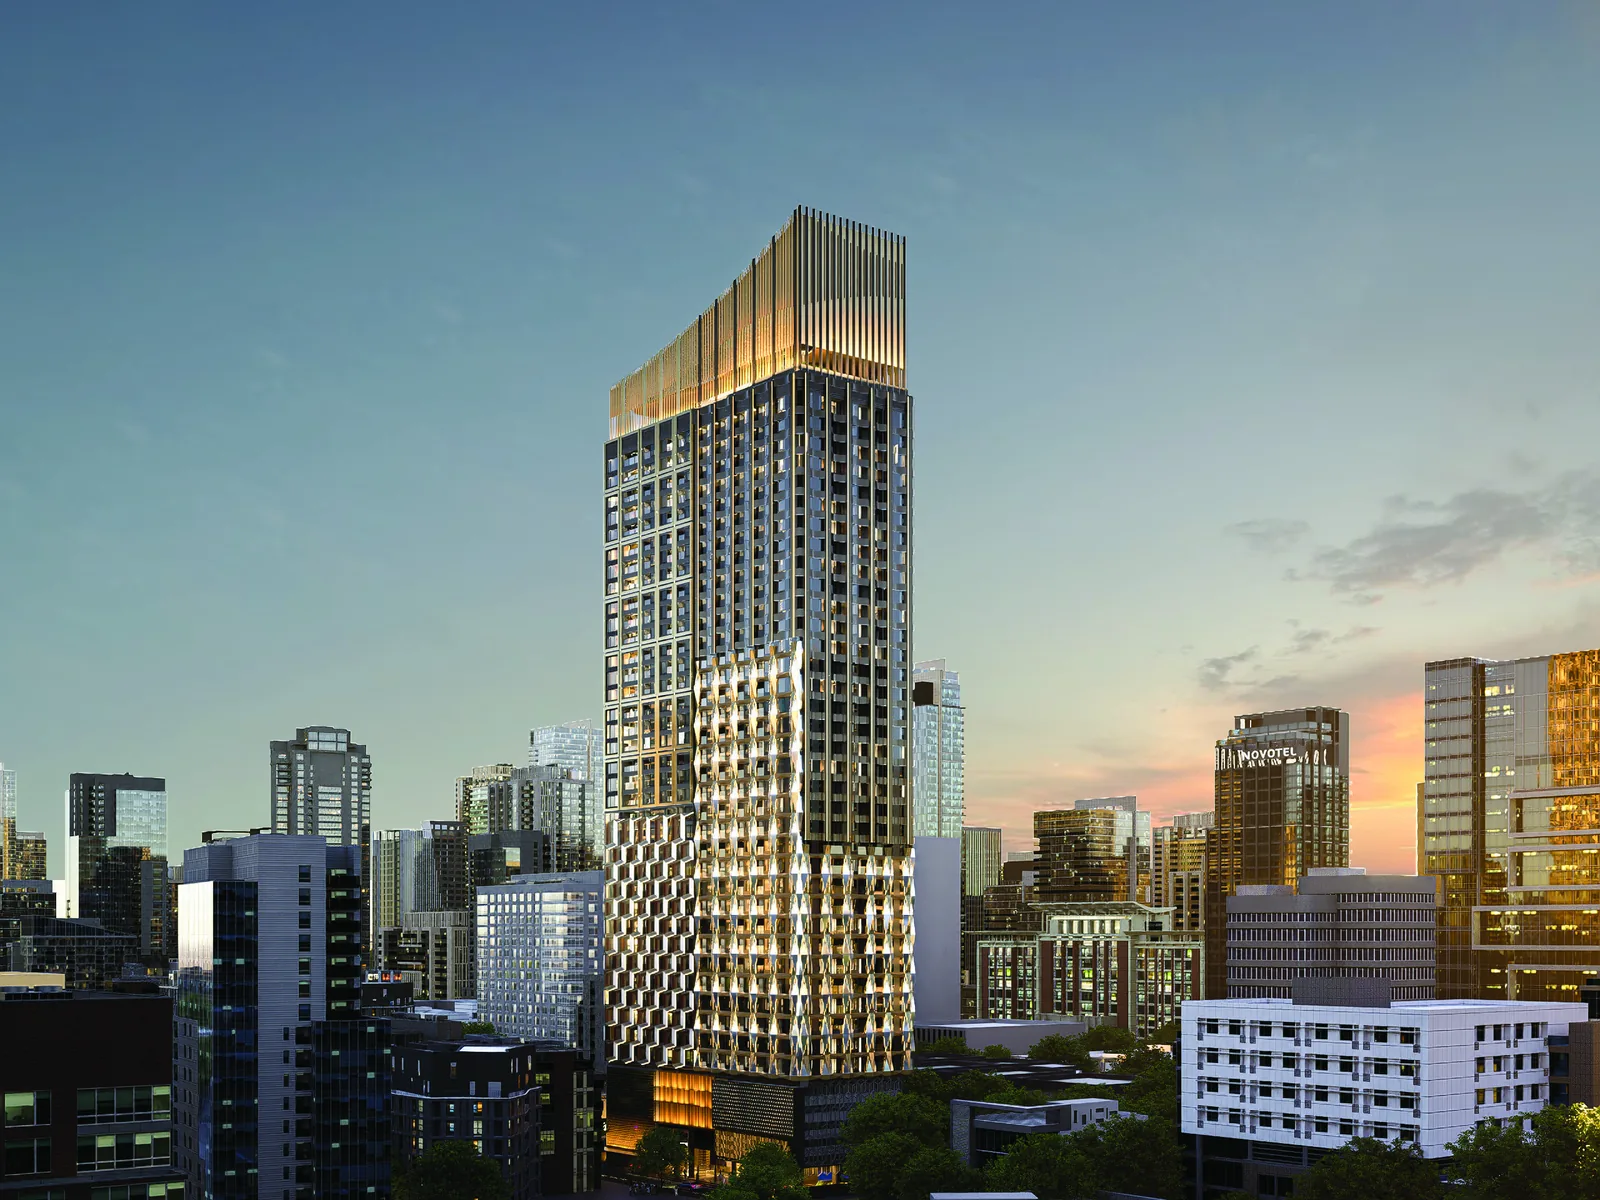
Time Square 11, Phnom PenhPhoto: developer/project materials
Condominium

Time Square 11 (Time Castle XI)

Phnom Penh · BKK3
MegaKim World Corp Ltd
Under construction
Off-plan high-rise residential condominium · 39 floors · 390 units
From $44,251Current availability and price need confirmationThe lowest public anchor is USD 44,251 on the Time Square Cambodia sales page, checked on 6 October 2026. Other current project pages show entry points around USD 49,168 to USD 64,000, so USD 44,251 should be treated as a promotional floor rather than guaranteed stock. The exact unit, discount, price and terms need written confirmation before reservation.
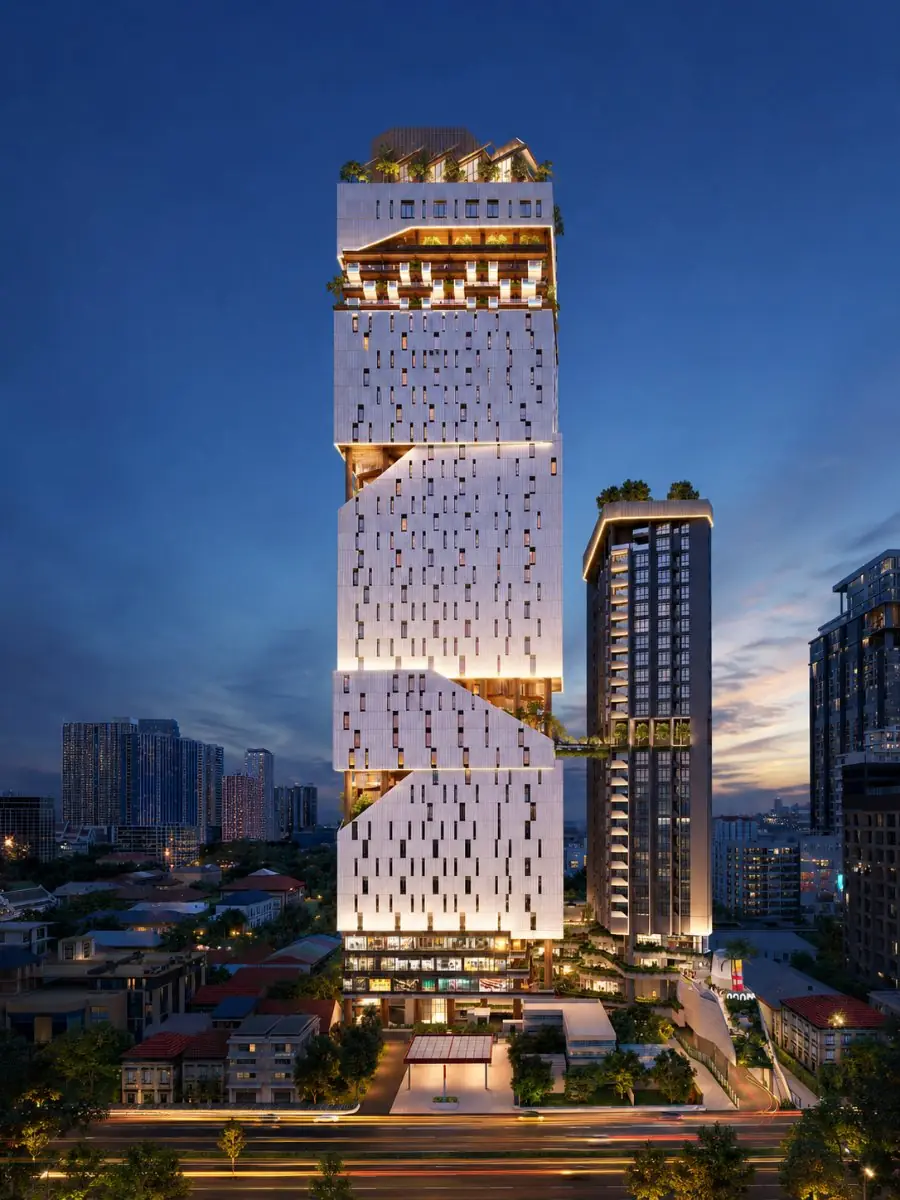
Kingston Royale, Phnom PenhrenderRender: developer/project materials
Condominium

Kingston Royale

Phnom Penh · Mean Chey
Kingston Estates
Under construction
Residential high-rise condominium · 36 floors · 310 units
Kingston Royale is a Kingston Estates residential project in Boeung Tompun, Mean Chey, Phnom Penh.
From $45,662Current availability and price need confirmationFrom USD 45,662 on the current IPS Cambodia project profile, checked on 6 October 2026. This is a lower market anchor from available listings, not a project-wide fixed price; the exact unit, discount, availability and payment schedule need to be reconfirmed before reservation.
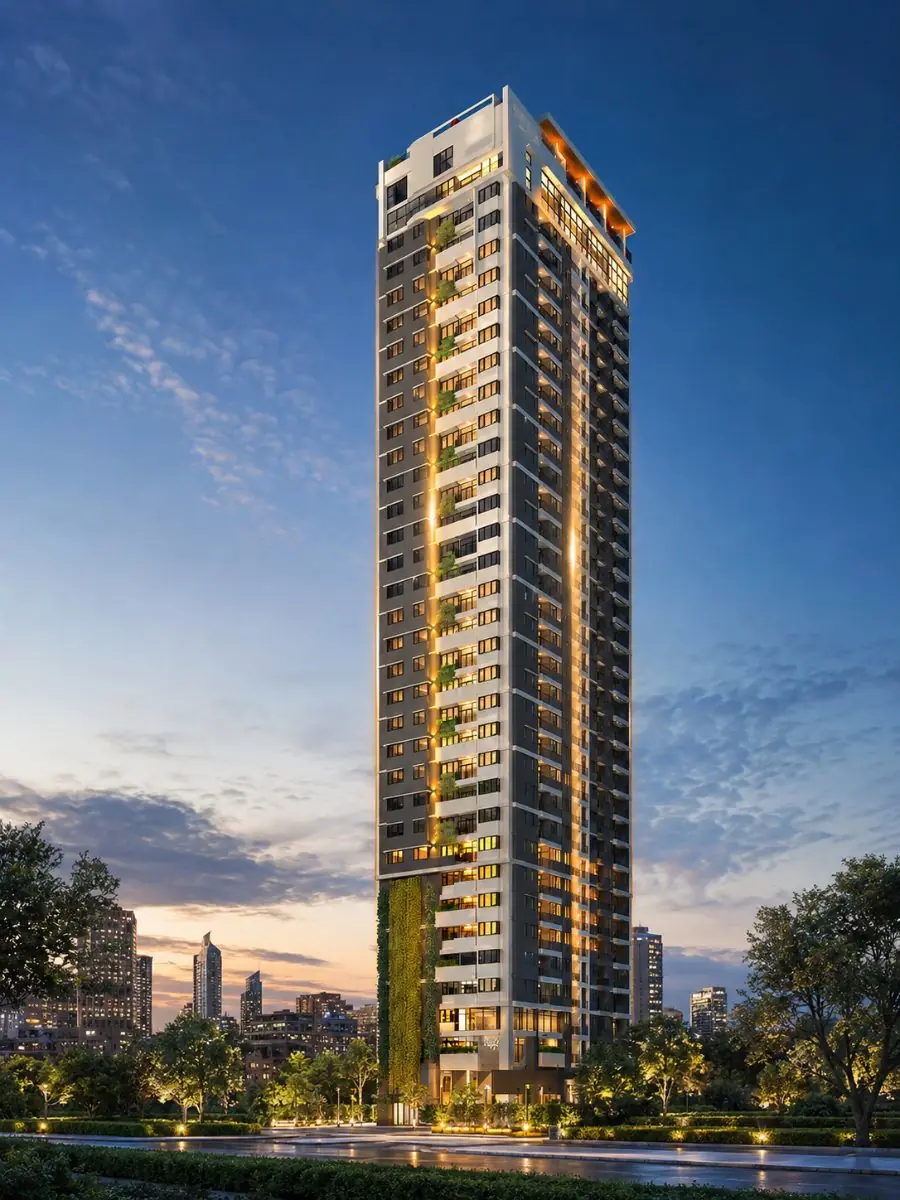
Completed KMH Residence tower on Street 208 in Daun Penh, Phnom PenhPhotos and plans: KMH Residence gallery on IPS Cambodia
Condominium

KMH Residence

Phnom Penh · Daun Penh
KMH Residence Cambodia
Completed
Residential high-rise · 25 floors · 120 units
KMH Residence is a completed urban condominium on Street 208 in Boeng Reang, central Daun Penh.
From $48,888Current availability and price need confirmationFrom $48,888 on the public FazWaz project page as of July 26, 2026. This is a lower market reference: unit availability, the current price and transaction terms must be confirmed separately with a specialist.
Render of the 24-storey LZ Sea View Premium tower in SihanoukvillerenderRender: LZ Sea View Premium project materials / ERA Cambodia
Mixed-use

LZ Sea View Premium

Sihanoukville · Sihanoukville
LZ Sea View Residences Ltd.
Under construction
Condominium, hotel and commercial high-rise · 24 floors
From $54,715Current availability and price need confirmationFrom $54,715 in current IPS Cambodia and FazWaz listings checked on July 26, 2026; the project's published price list starts at $64,480. This is a lower market anchor, while availability, the final price and terms for a selected residence must be checked and confirmed separately with a specialist.
Time Square 4 / Time Square III, Toul Kork, Phnom PenhPhoto: KH Properties, specific to the project Time Square 3 listing
Mixed-use

Time Square 4

Phnom Penh · Toul Kork
Megakim World Corp. Ltd
Completed
Completed mixed-use condominium and office tower · 25 floors · 280 units
From $58,000Current availability and price need confirmationFrom $58,000 in an active Realestate.com.kh listing checked on August 4, 2026. This is a lower resale-market reference for one advertised unit, not a fixed project price: the apartment, measured area, condition, furniture, title, availability and transaction terms must be confirmed separately.
Borey Lorn City Lotussea, Lorn City Lotussea and Lotussea Town homes and shophouses near National Road 4, SihanoukvillerenderRenders: official Lorn City Group / Borey Lorn City Lotussea materials
Mixed-use

Borey Lorn City Lotussea Town

Sihanoukville · Sihanoukville
5LH Lorn City Development Co., Ltd
Under construction
Large-scale residential and commercial township
From $68,500Current availability and price need confirmationFrom $68,500 in the project's current public offers checked on July 25, 2026. This anchor applies to selected completed link villas; the exact price, availability, house model, plot and transaction terms must be confirmed separately with a specialist.

Developer instalments can reduce the amount of capital committed on day one. The useful question is not how small the deposit looks, but what the plan costs, when the balance is due and what rights you have along the way.

First payment
from 10–20%*
depends on the project and the plan
The whole schedule
shown upfront
including the balloon before handover

An instalment plan is a cash-flow tool, not a substitute for due diligence. It may let you keep liquidity for another investment, relocation or business, while creating a multi-year obligation to one developer and one project.

This page is designed to stress-test that obligation. It separates the attractive headline from the contract: total price, capital locked at each stage, handover balance, default clauses, ownership route and the practical options if you need to exit early.

KEY TAKEAWAYS

What to take away

5 points · about 45 sec

The main ideas to keep in mind as you read.

  1. The first deposit and monthly instalment reveal only part of the commitment; the balance due at handover, transaction costs and the dates on which payments cluster determine whether the purchase is affordable. Test the full schedule against a cash reserve, not just regular income.

  2. A longer developer plan may preserve liquidity now while extending exposure to construction and the developer’s performance. A shorter term shifts more cash out sooner but reduces the period of unpaid obligations.

  3. The address, ownership route and financing term answer different questions: a desirable location does not validate the unit’s price, foreign title eligibility or payment schedule.

  4. Commercial instalment packages need a separate assessment of the property, operating income and any promised buyback; the promoter’s payment schedule cannot establish the value or security of the other promises.

  5. USD pricing can simplify comparisons without removing construction, resale or counterparty risk.

Nova Asia AI assistant

Let’s explore this page together

How much you need, and what fits

Set the cash you want to commit now, your monthly ceiling and preferred term. The calculator estimates a sustainable purchase budget rather than simply matching the lowest advertised deposit.

Figures are indicative. Exact terms and schedule are confirmed against the developer’s current price list.

ODOM Tower, BKK1
Income · programme

ODOM Tower

LocationBKK1, Phnom PenhTypeCommercialProgramme8% net*, 110% buyback*Entryhigher

*Contractual programme, limited pool. Terms verified.

Open the project →

How the installment plan and schedule work

How an installment purchase works

Booking

A reservation fee removes a specified unit from sale for a limited period. Ask for the unit number, agreed price, reservation expiry and refund rules before sending funds.

First payment

The sale contract then sets the initial contribution and activates the longer schedule. This is the point to confirm whether the quoted price includes any financing premium or excludes available cash discounts.

Scheduled installments

Payments may be monthly, quarterly or tied to construction milestones. Record the due dates in your own currency and allow for transfer time, bank charges and exchange friction.

Balance before handover

Many plans retain a material percentage for completion or handover. Treat this balloon payment as a committed liability from day one, not as a future problem to solve.

Handover and registration

Completion should trigger inspection, defect reporting, final settlement and the agreed title process. The contract needs to distinguish physical handover from legal registration.

If a payment is late

Late-payment provisions can include interest, notice periods, suspension or termination. Understand whether the developer must give you time to cure the default and what happens to capital already paid.

How to read the payment schedule

Start with the all-in acquisition cost and then map when each part becomes payable. Include reservation, initial contribution, instalments, handover balance, registration, fit-out, management setup and transaction costs. This reveals the true liquidity requirement, which is often different from the neat monthly figure shown in a sales illustration.

Next, consider your position at different exit dates. How much will you have paid by month 12 or 24? Can the contract be assigned? Would a new buyer pay the same price when the developer may still have unsold stock? The schedule is not only about affordability; it determines how exposed you are if your strategy changes before completion.

StageWhenApprox. share
Bookingat unit selectionfixed fee
First paymentat contract≈ 10–30%*
Installmentsduring buildequal payments*
Balance at handoverat completion0–30%*

*Shares are indicative and project-specific; exact schedule is in the developer contract.

Plan builder: pick a schedule

Use the plan builder to compare how quickly equity accumulates under each structure. Move through the timeline and watch three numbers: cash already paid, capital still committed and the lump sum due at handover. A plan that preserves liquidity for two years may be useful, but it also leaves more exposure concentrated at the end.

Illustrative price of $70,000. Your project is calculated from the developer’s current price list and contract; the balloon payment is shown separately.

Terms in plain words

QUESTIONS ABOUT THIS TOPIC

A closer look

3 questions · open to read

Practical follow-up questions that go beyond the basics.

Does a construction-milestone schedule reduce the risk compared with fixed dates?

Milestone payments can link the release of money to visible construction progress, while calendar payments may continue regardless of how the site advances. Neither arrangement is protective by itself: the agreement must define how each milestone is verified and what happens if it is missed.

Can I take possession if the building finishes before my final instalment?

Only if the developer’s contract permits it. A long payment term does not automatically give you the keys before the balance is settled. Ask whether occupation, title registration and the final payment fall on different dates. If early possession is offered, clarify who bears running costs and what rights remain restricted until settlement.

Should I use projected rent to finance the balance due at handover?

Projected rent is an uncertain supplement, not a dependable repayment source. Even a project in an established rental neighbourhood must be completed, handed over, furnished where needed and occupied before cash arrives. Compare the handover date with the payment deadline, then model a construction delay and a period with no tenant; a reserve or independently available capital is more credible than assuming the apartment will immediately pay for itself.

Which plan fits your goal

A long 0% schedule maximises retained liquidity, a back-loaded plan concentrates risk at handover, and a short plan builds paid equity faster. The best fit depends on opportunity cost, income visibility, exit flexibility and confidence in the developer—not on the longest term alone.

CriterionLong 0%With balloonShort
Monthlylowermediumhigher
End-risklowerhighnone
Overpaymay be priced independsless
For whommonthly budgetexpecting incomehave capital

Foreign ownership, briefly

Eligible condominium apartments may be registered to a foreign buyer under an individual strata title. The market often refers to this as freehold ownership, but eligibility depends on the legal status of the building, the position of the unit and the permitted foreign quota.

An instalment contract and a registered title are not the same thing. During construction, you may hold contractual rights to a future unit while title is issued only after completion and settlement. The agreement should explain what you can assign, what the developer must deliver, when registration occurs and how paid amounts are treated if either party fails to perform.

More on the market and ownership →

Installment risks, and who it suits

What feels risky about installments

A hidden balloon

A modest monthly amount can conceal a large completion liability. Read the plan as percentages of the full price and identify the exact cash required at handover before judging affordability.

What if it is not built

With off-plan property, your payments are made before the asset is complete. Review land and project documents, delivery history, construction evidence and the remedies available if completion is delayed.

What if I miss a payment

Cross-border transfers, income changes or simple oversight can cause a missed due date. Check cure periods, penalties, termination rights and whether assignment is possible before the contract reaches default.

Who installments suit, and who they don’t

A fit if you

  • staged deployment improves your wider cash position and you can fund every later obligation without relying on optimistic rent or resale.
  • you are comfortable taking developer and construction exposure in return for a lower initial capital commitment.
  • the agreement gives you clear information on title, assignment, default, completion and the treatment of money already paid.

Not yet, if you

  • the plan only works after assuming a future loan, refinancing event or quick flip that has not been secured.
  • most of your liquid capital would be tied to one unfinished project with no reserve for delays or personal needs.
  • the developer will not provide a complete schedule and draft contract before asking for a non-refundable reservation.

The key installment risks

Large balance

A back-loaded plan can preserve liquidity now while creating a completion payment that is too large to fund when it falls due.

Priced-in overpay

The economic cost of 0% financing may appear in a higher unit price, reduced discount or less favourable inventory.

Default & exit

A missed instalment can trigger penalties or termination, while assignment may be restricted precisely when you need an exit.

Checklist before you reserve a plan

When comparing developer finance, test the contractual mechanics from reservation through final settlement—not just the headline rate.

Done: 0 / 7 · 0%

Your ticks are saved in your browser. This is an educational list, not legal advice — the contract is reviewed by an independent lawyer for your specific deal.

Projects with installment plans

Kingston Royale

Kingston Royale represents the straightforward use case for developer finance: a residential purchase in Phnom Penh spread across a stated 36-month, 0% schedule. For a buyer who wants to retain capital outside the property during construction, the term can reduce the amount tied up in the early stages.

The comparison should be made against the project’s cash price and not against the monthly figure alone. Ask whether full payment attracts a discount, which units qualify for the plan, how much is due before work is complete and whether delayed construction changes the payment dates. The contract should also state how cancellation, assignment and late payment are handled.

A three-year schedule is only as valuable as the project behind it. Review delivery history, current works and the eventual rental proposition. Kingston Royale may suit a buyer prioritising measured capital deployment, but the plan should not be used to justify a unit that would otherwise be overpriced or difficult to rent.

Project page →

Time Square 9

Time Square 9 adds a location and ownership dimension to the financing decision. BKK1 is a central Phnom Penh district with an established international profile, while the supplied terms refer to a 45-month schedule and eligible condominium freehold. These features appeal to an overseas buyer, but they solve separate parts of the decision.

The 45-month term affects liquidity; BKK1 affects the demand thesis; strata ownership affects legal control. Test each independently. Compare the unit price with completed BKK1 stock, confirm the foreign quota and title route, and identify how much of the price remains unpaid when the building is expected to complete. If the project finishes before the schedule ends, clarify whether occupation or title requires accelerated settlement.

Exit flexibility matters on a long plan. Ask whether the contract can be assigned, what fee applies and whether the developer has a right to approve the new buyer. A central address may support resale, but it does not remove competition from the developer’s own remaining inventory.

Project page →

ODOM Tower

ODOM is not a low-ticket residential instalment story. It is a higher-value commercial proposition in which financing, an income programme and a stated buyback mechanism may be packaged together for a limited pool of units. That makes the contract more important, not less.

Separate the components. First, evaluate the commercial unit and price without the programme. Second, map the payment schedule and capital at risk. Third, analyse the party promising the stated net payments and 110% buyback: calculation base, duration, conditions, security and ability to perform. A contractual mechanism can reduce uncertainty only to the extent that it is clear and enforceable.

For a larger investor, ODOM may offer structured exposure and several potential exit routes. It also brings concentration, operator and counterparty risk that a simple apartment plan does not. The right question is not whether instalments make the entry look easier, but whether the complete commercial case works without depending on the promotional programme.

Project page →

Why Cambodia, and an expert view

Why Cambodia for installments

Cambodian developers commonly use direct payment plans to sell off-plan condominiums. This can give an overseas buyer access to a USD-priced property without arranging a local mortgage, and it allows capital to be deployed gradually during construction. The range of plans—long monthly schedules, milestone payments and split deposit/balance structures—can be commercially useful for buyers with predictable income or assets that they do not want to liquidate immediately.

The trade-off is counterparty exposure. The developer, rather than a bank, controls the timetable, default remedies and delivery of the asset. A 0% label does not prove that the unit is competitively priced, and a long term does not improve the underlying project. Buyers still need to examine the developer’s completed work, title structure, construction progress, management plan and resale market. USD denomination simplifies the arithmetic; it does not eliminate project or liquidity risk.
Expert view

Elvira Shamuratova

I ask buyers to look past the first deposit and follow the plan all the way to handover. The important questions are what remains at the end, what happens if a payment is late, and whether the unit will be managed and saleable after completion. A beautiful monthly number is not enough if the wider plan does not fit the buyer’s life.

Elvira Shamuratova
Founder of Elvira Cambodia · Associate Director at Pointer Property · strategic partner of NovAsia
Expert profile →

Key takeaways

Compare like for like

Ask for the cash price and instalment price of the same unit on the same date. The difference between the two totals is a better measure of financing cost than a headline claiming zero interest.

Map the exposure

Match cumulative payments to verified construction stages. When most of the price is due well before completion, the developer's documents, financial capacity and buyer remedies deserve much closer scrutiny.

Frequently asked questions

How is an installment plan different from a mortgage?
A developer plan is part of the sale agreement and is funded by the developer’s willingness to accept payment over time. A mortgage is a separate bank loan with underwriting, interest and security. The two structures provide different protections and default processes.
Is 0% real?
The contract may genuinely charge no separate interest. Still compare the financed price with the cash price and available discounts, because the cost of time may be reflected elsewhere in the deal.
What is the balloon before handover?
A balloon is a large amount left for completion, handover or title transfer. It keeps earlier payments lower but concentrates liquidity risk on one date.
Can I sell before the plan ends?
Some contracts permit assignment before the schedule is complete. The developer may require consent, a fee, a minimum paid percentage and full identity checks for the incoming buyer.
What happens if I default?
The agreement should state the grace period, late charges, notice procedure and termination consequences. Ask whether you can cure the breach, restructure the schedule or assign the contract before paid capital is forfeited.
Is the installment price different from the cash price?
Yes. Developers may offer a cash discount, a separate financed price or different unit selection. Compare the total amount payable and the exact unit, not just the stated interest rate.
Can I arrange installments remotely?
Selection, live viewing, due diligence and parts of signing can often be handled remotely. The workable process depends on the developer, identity checks, payment route, powers of attorney and title-registration requirements.
Which Cambodia projects offer installments?
Payment plans are most common in off-plan condominium developments and may also appear in selected commercial or completed inventory. Terms vary by unit, sales phase and campaign, so current documents must replace general market claims.
Which currency fixes the purchase price, and how is the exchange rate applied?
The contract should distinguish between the currency in which the price is fixed and the currency you are allowed to use for payment. It should also identify the exchange-rate source, the conversion date and any bank or payment-processing fees. Model a less favourable exchange-rate scenario before committing, especially when instalments run for several years.
Who legally owns the property while I am still paying the developer?
This depends on the local ownership system and the wording of the sale contract. Title may remain with the developer until completion and full payment, or the buyer may receive a registered interest earlier; the contract should also explain whether the property can be mortgaged or otherwise encumbered. Before signing, confirm what happens to your payments if the agreement is cancelled or either party defaults.
Which payments will I need to make before the keys are handed over?
The advertised entry payment is usually only the first step. Ask for a dated schedule showing the reservation deposit, down payment, construction-linked instalments and final handover balance, then add taxes, registration charges, utility connections and any service fees due before or at handover. Check the figures for the specific project, because some costs may sit outside the developer’s headline price.
What happens to the payment plan if the developer delivers the project late?
A construction delay does not always give the buyer an automatic right to stop paying. The contract should state the grace period, whether instalments can be suspended, what compensation may apply and when cancellation or a refund becomes available. Read those clauses before purchase rather than relying on a sales representative’s verbal explanation.
Who carries the risk while the development is under construction?
The buyer carries meaningful timing and completion risk whenever money is paid before a finished, registrable unit is delivered. Land, approvals, construction history and contractual remedies can reduce that exposure but cannot remove it.
Are Asian instalment plans the same as Dubai payment plans?
No, because project registration, buyer-money controls and title mechanics differ by jurisdiction. Treat each country as a separate legal system and verify who receives the funds, when ownership becomes registrable and what protection applies after delay.
What is a reasonable down payment on an overseas instalment plan?
There is no universal percentage that is automatically safe. Judge how much capital is exposed before visible construction progress, how large the final balance is and whether you still have a reserve after each payment.
Which clauses matter most in a developer instalment contract?
Focus on total price, dates, beneficiary account, default remedies for both parties, assignment, refund, termination and handover documents. The clause covering developer delay is just as important as the clause covering a late buyer payment.
Can you settle the plan early and negotiate a discount?
Sometimes, but the revised price and early-settlement terms should be documented before you transfer the balance. Confirm that future charges disappear and that title or handover can proceed immediately after payment.

Decision helper

Situation

Installment risks, and who it suits

Next step

A hidden balloon A modest monthly amount can conceal a large completion liability.

Keep in mind

Read the plan as percentages of the full price and identify the exact cash required at handover before judging affordability.

Situation

Checklist before you reserve a plan

Next step

When comparing developer finance, test the contractual mechanics from reservation through final settlement—not just the headline rate.

Keep in mind

Your ticks are saved in your browser.

Situation

Build a schedule for your budget

Next step

Share the capital you want to commit now and your monthly ceiling.

Keep in mind

We will compare live plans, highlight the completion balance and explain where each structure may fail.

Situation

Other guides by budget and goal

Next step

Prices, terms and project-specific programmes are confirmed against the developer’s current price list, offer and contract.

Keep in mind

Detailed ownership, tax and payment guidance is maintained on NovAsia’s dedicated legal pages.

Build a schedule for your budget

Share the capital you want to commit now and your monthly ceiling. We will compare live plans, highlight the completion balance and explain where each structure may fail.

Other guides by budget and goal

Sources0

    Prices, terms and project-specific programmes are confirmed against the developer’s current price list, offer and contract. Detailed ownership, tax and payment guidance is maintained on NovAsia’s dedicated legal pages.

    Updated: 2026-08-03